
Why Does Festive Season Business Debt Become a Post-Festival Crisis for MSMEs?
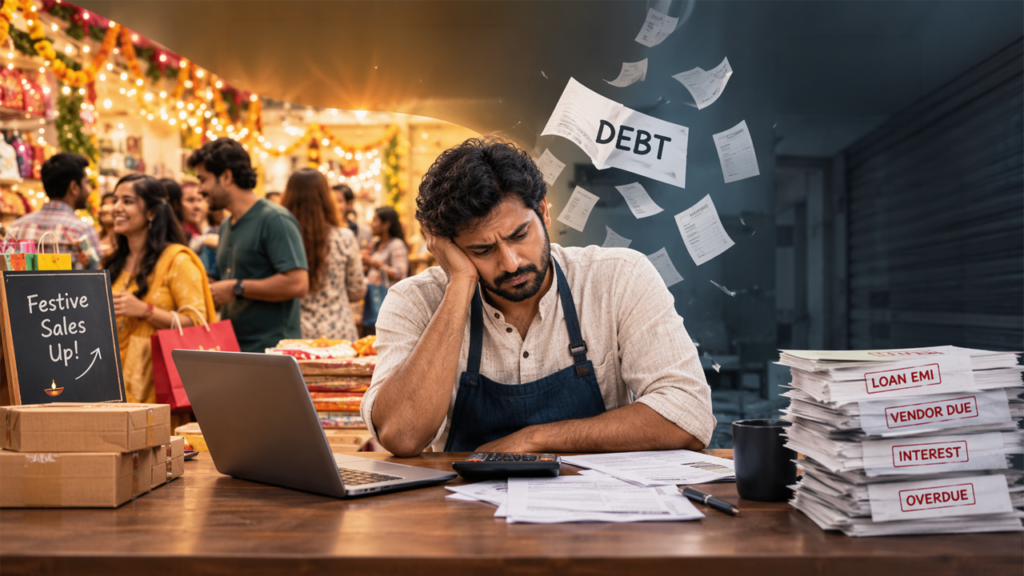
Festive season business debt for year-end turns into a January crisis because MSMEs borrow in September and October and get paid in December and January (45-90 days late). During this time, EMIs, supplier dues, and GST deadlines fall in between, creating a crack. The gap is a timing mismatch, not a profitability problem, which is exactly why it is preventable.
Knowing the happenstance of festive debt matters for businesses because the borrowing is rational, as festive demand is real. What fails is the repayment calendar built around it. Under Section 15 of the MSMED Act, buyers must pay MSMEs within 45 days of accepting goods or services, and Section 16 makes them liable for compound interest at three times the RBI bank rate.
This blog covers why the post-festive debt crunch repeats every year, a pre-Diwali debt management plan you can build now, a real recovery case study, verified sector data, and your legal options when buyers delay payment.
Festive Season Debt Hangover is the predictable cash shortfall that hits MSMEs roughly 30–90 days after peak festive sales. Between August and November, a business borrows for inventory, contract staff, packaging, advances to suppliers, and marketing. Industry estimates suggest 60–70% of SMEs report difficulty securing adequate working capital during the festive season, customer payment delays stretch beyond 45 to 60 days, and around 73% struggle to optimise cash flow during peak sales periods.
The opportunity is genuine. CAIT estimated Diwali 2025 trade at a record ₹6.05 lakh crore — ₹5.40 lakh crore in goods and ₹65,000 crore in services. With Dhanteras on 6 November and Lakshmi Puja on 8 November 2026, the buying cycle for this year’s season is beginning now.
Lenders have historically expected festive-period MSME loan disbursals to rise 20–25% year on year. That money goes out in Ashadh-to-Kartik months. Repayment schedules, however, start immediately, usually within 30 days of disbursal.
Distributors and corporate buyers clear festive invoices last. According to the Economic Survey tabled ahead of Budget 2026, roughly ₹8.1 lakh crore remains locked in delayed payments owed to MSMEs.
Demand collapses post-Diwali, but fixed obligations do not. Salaries, EMIs, rent, GST and advance tax all continue. Unsold festive inventory becomes dead capital.
Period | What happens | Risk level | Action to take now |
Aug–Sep 2026 | Inventory orders, supplier advances, loan applications | Moderate | Set a borrowing ceiling; map repayment dates |
Oct–Nov 2026 | Peak staffing, marketing spend, credit sales | High | Tighten credit terms; document every invoice date |
Dec 2026 | Sales fall; EMIs and salaries continue | Critical | Chase receivables aggressively; flag stress to lenders |
Jan–Feb 2027 | Multiple dues converge; defaults begin | Severe | Restructure — before the account is classified |
Here’s how you should plan for the upcoming festive season for your business:
List each festive expense and the realistic date you will be paid for the sales it generates. If the gap exceeds 60 days, that expense needs longer-tenure funding instead of a 90-day facility.
Cap borrowing against conservative collections, not optimistic sales. Test the number against a 20% sales miss and a 30-day collection delay simultaneously. If the plan breaks, the borrowing is too high.
Different business needs require different financing instruments. Inventory purchases are best suited to cash credit or working capital limits, while approved invoices can be financed through TReDS discounting. Plan accordingly.
Multiple small high-interest loans are the single biggest driver of post-festive collapse. Consolidation negotiated in September carries a very different tone and outcome than one attempted in February.
A structured review of your obligations through SingleDebt Business’s debt management services is best done now, not after the first missed EMI.
Review recurring costs before adding new debt. Our guide on five ways to reduce your debts and outgoings covers the fastest levers.
A 40-worker textile unit borrowed ₹48 lakh across four facilities before Diwali, including one bank OD, two NBFC term loans, and one merchant-cash advance at an effective 26%. Festive sales met the target, but 62% of dispatches went to distributors on 60-day credit, and payments slipped to 95 days. By January, monthly outflows of ₹6.8 lakh met collections of ₹3.1 lakh.
The solution: The owner entered a Company Informal Debt Arrangement (CIDA) to restructure the business’s debt around its actual cash flow. The plan consolidated the two costliest facilities into a longer-tenure obligation, negotiated a revised OD repayment schedule with the bank, pursued delayed receivables from two buyers, and imposed a 90-day freeze on discretionary spending.
The unit entered the next festive season with a pre-agreed borrowing ceiling.
The festive debt hangover is not caused by bad businesses or bad decisions. It is caused by a calendar mismatch that repeats with complete predictability: money out in October, money in by January, obligations due in December. Every owner who has been through it knows the shape of it.
The businesses that break this cycle aren’t the ones that borrow less. They’re the ones that decide how they’ll repay before they decide how much to borrow.
An MSME should start planning at least 8 to 10 weeks before Diwali 2026 (8 November), which means September. Planning after the season is damage control.
A practical rule is keeping total monthly EMIs below 30–35% of conservatively estimated post-festive collections, stress-tested for a 20% sales shortfall.
If buyers don’t pay within 45 days, then statutory interest accrues automatically under Section 16. File a reference on the MSME ODR Portal; Udyam registration is mandatory.
Rarely. Effective costs often exceed 24–30%, and daily deductions bite hardest in the post-festive lull.